

Previous post in this series: A Better Journey, Not Just a Faster One
For the third article in this series, I am returning once more to Rory Sutherland. At this point, I may owe him either a royalty or a drink.
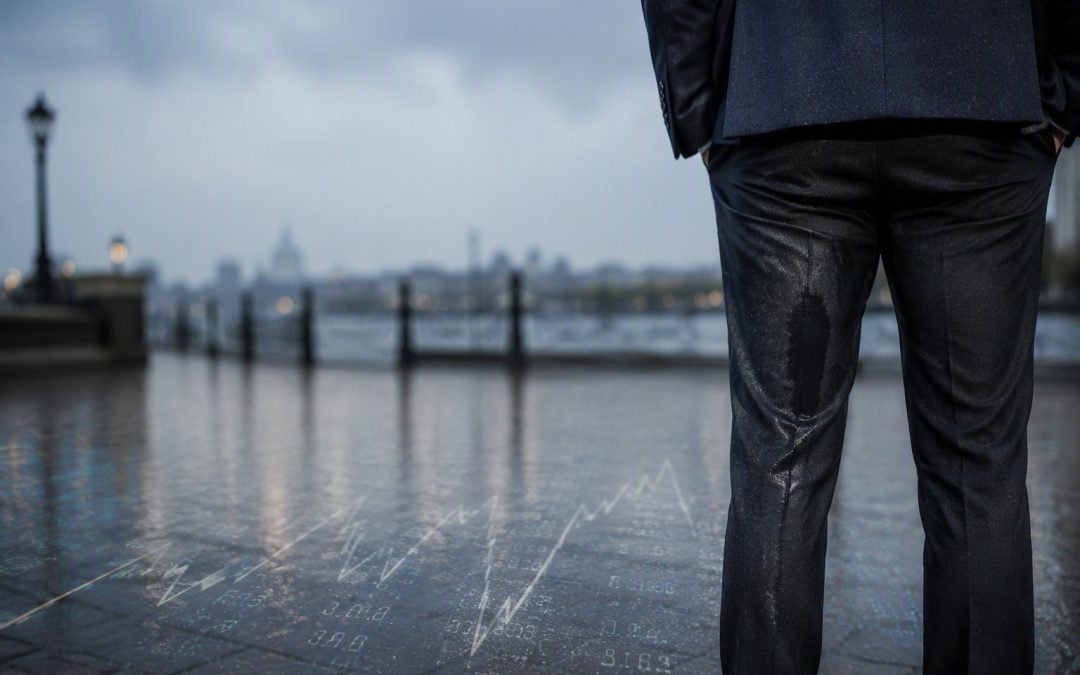
One story I remember from his talk concerned a rather unfortunate patch of water on his trousers shortly before he was due to speak. Despite his best efforts, he could not get it dry. Then he noticed it was raining outside.
So, rather than continuing to dry the wet part, he went outside and got the rest of himself wet. The original problem had not changed, but its meaning had. He no longer looked as though he had suffered an embarrassing accident. He simply looked like someone who had been caught in the rain.
His solution was wonderfully backwards: if you cannot dry the wet bit, wet the dry bit.
There is a serious idea beneath the humour. Facts rarely arrive without context, and context can completely change how we interpret them. This is particularly true when the facts concern money.
A number on its own can tell the wrong story
Imagine opening an investment statement and seeing that its value has fallen by £40,000. That is a meaningful amount of money, and there is no value in pretending otherwise. But the figure alone leaves several important questions unanswered. How large was the portfolio? Over what period did the fall occur? Had money been withdrawn? What was happening in markets generally? Most importantly, when will the money be needed?
A £40,000 fall on a £200,000 portfolio is very different from the same fall on £2 million. A temporary decline in money intended for use decades from now has a different significance from a fall in money needed next year.
Providing context does not make the loss disappear. It helps us understand what the number means and whether anything needs to be done.
Unfortunately, financial headlines are rarely rewarded for context. “Markets behave broadly as long-term investors expected” lacks a certain urgency. “Billions wiped off shares” tends to attract more attention, despite revealing remarkably little about what an individual should do next.
The same money can feel entirely different
Context also changes how we experience spending.
A £10,000 holiday paid from a current account may feel extravagant. The same holiday paid from a sum deliberately set aside for travel can feel like carrying out the plan. The pounds are identical. What has changed is the story attached to them.
This is close to what behavioural economists call mental accounting: our tendency to place money into different imaginary pots and treat it differently according to its source or purpose. A tax refund is no more or less valuable because it feels like “free money”, and an investment gain is still our money even if we did not earn it through work.
Used thoughtfully, however, giving money a purpose can be helpful. A separate reserve for home repairs, family gifts or planned holidays can make spending more deliberate. It can also prevent every larger purchase from feeling like an unexpected raid on long-term security.
The account label has not created more money. It has created useful context.
Falling values do not always mean a failing plan
Retirement can make context particularly important. During working life, progress is often judged by whether pensions and investments are growing. Once withdrawals begin, account values may rise slower than before, fluctuate or reduce over time. Seen without context, that can feel like failure.
But a retirement plan is not designed simply to preserve the highest possible number forever. It may be designed to provide income, fund travel, help family or allow work to finish sooner. If money is being used sustainably for the purpose it was accumulated, a reducing balance is not automatically evidence that something has gone wrong.
Equally, “it is part of the plan” should never become an excuse to ignore warning signs. Spending, investment performance, inflation, tax and changing circumstances still need reviewing. Context should improve judgement, not silence questions.
Reframing is not the same as pretending
There is an obvious danger in all this. Almost any unwelcome fact can be made to sound better with sufficiently inventive language. That is not financial planning, that is public relations with a calculator.
A market loss remains a loss. A tax charge remains a cost. An unaffordable level of spending does not become sensible because we rename it “living for today”.
Useful reframing does not alter the facts. It places them alongside the purpose, timescale and wider circumstances needed to interpret them properly. That distinction matters. The aim is not to feel better regardless of reality. It is to see reality more completely.
Seeing the whole picture
Sutherland’s wet-trouser solution worked because he changed what the evidence appeared to mean. With money, we need to be more careful, but the underlying lesson survives: before reacting to one figure, look at the picture around it.
What appears alarming in isolation may be manageable within a long-term plan. What appears reassuring may deserve more attention once its risks are visible. The right context will not always produce the answer we would prefer, but it should produce a better-informed one.
If a figure in your financial plan, investment statement or pension paperwork concerns you, please ask us about it. We will explain what it means, how it fits into the wider plan and whether it requires action. Questions are always better than allowing one unexplained number to tell the whole story.
If Rory has given you as much food for thought as he has me, his book Alchemy is well worth a read. I would encourage you to buy your own copy though, borrowing mine might bring forward the point at which I owe him both the royalties and the drink.
Disclaimer: This article contains information from sources believed to be reliable but no guarantee, warranty, or representation, express or implied, is given as to its accuracy or completeness. Howard Wright Ltd does not undertake any obligation to update or revise any future statements. Past performance is not a reliable indicator of future results. Investments can go down as well as up and actual results could differ materially from those anticipated. This article is for information purposes only and has no regard to the specific investment objectives, financial situation or particular needs of any person as such, the information contained in this article is not intended to constitute, and should not be construed as, investment or financial advice. Appropriate personalised advice should be taken before entering into any transactions. No responsibility can be accepted for any loss arising from action taken or refrained from based on this publication. Howard Wright Ltd is Authorised and regulated by the Financial Conduct Authority.